SaaS Business Valuation: Methods, Multiples & Key Metrics
Revenue multiples are usually the first thing that comes up when discussing SaaS valuations. And for good reason. Recurring revenue makes SaaS businesses relatively easy to benchmark against other companies, even when they’re not yet profitable.
But knowing that SaaS companies trade at a certain multiple doesn’t tell you much about what a specific business is worth.
A SaaS business valuation requires a closer look at the company’s financial performance, growth prospects, customer retention, and the quality of its recurring revenue. It also requires choosing the right valuation methodology and, perhaps more importantly, identifying comparable companies that actually resemble the business being valued.
This guide covers the main SaaS valuation methods, how to interpret revenue and EBITDA multiples, and the financial metrics that influence valuation. We’ll also look at how the approach changes across funding stages and work through a practical valuation example.
-
SaaS valuation combines market multiples with financial performance and projections. Revenue and EBITDA multiples provide market-based valuation benchmarks, while DCF offers an alternative perspective when cash flow forecasts are sufficiently reliable. Finro's Forecast-Weighted Multiples Method applies comparable-company multiples to weighted projected financial performance.
-
Revenue projections are central to valuing early-stage SaaS companies. Current ARR may not adequately represent a startup's growth potential. Finro's User Journey Method builds revenue forecasts from customer acquisition, conversion, retention, and monetization assumptions rather than relying exclusively on top-down growth estimates.
-
Relevant comparable companies matter more than generic SaaS industry multiples. Finro's Multi-Niche Comps Analysis breaks down the startup's business model into relevant niches and benchmarks each against public companies, private companies, and M&A transactions to establish market-derived valuation multiples.
-
Forecast weighting and company-specific risks influence the final valuation. Finro assigns greater weight to near-term financial projections and progressively less weight to later forecast years. The resulting market-based valuation is then adjusted for relevant company-specific risks and discounts.
Topics covered in this analysis
How Is a SaaS Business Valued?
The starting point for valuing a SaaS company is understanding its business model and financial performance, particularly recurring revenue, growth, and profitability. Historical and current financials establish the baseline for the analysis, helping assess whether the company’s growth assumptions and financial projections are realistic.
For established SaaS companies, profitability and historical performance may provide a reliable basis for valuation. For early-stage startups, where current revenue may not fully reflect the company’s growth potential, projected financial performance becomes particularly important. The objective is to connect the company’s existing financial position with a defensible forecast of its future performance.
Enterprise Value vs. Equity Value
Before calculating a valuation, it’s important to distinguish between enterprise value (EV) and equity value.
Enterprise value represents the value of the company’s operating business, independent of how it is financed. Equity value represents the value attributable to shareholders after accounting for debt, cash, and other relevant adjustments.
The basic relationship is:
Equity Value = Enterprise Value − Debt + Cash
This distinction matters because revenue and EBITDA multiples generally produce an enterprise value, not an equity value. Founders negotiating an investment or acquisition need to understand which value is being discussed.
How Finro Approaches SaaS Valuation
SaaS valuation involves more than applying a revenue multiple to a company’s latest financial results. A credible valuation must consider historical performance, future growth potential, relevant market benchmarks, and the risks associated with achieving projected results.
At Finro, we begin by analyzing the company’s historical and current financial performance. This establishes the baseline for developing five-year financial projections, connecting expected revenue growth to customer acquisition, conversion, retention, pricing, and other underlying business drivers.
We then identify relevant market benchmarks through our Multi-Niche Comps Analysis, examining comparable companies and transactions across the technology niches that best represent the business.
Our Forecast-Weighted Multiples Method brings these elements together by applying market-derived valuation multiples to a weighted average of projected revenue or EBITDA, with greater emphasis on near-term performance. We then adjust the preliminary enterprise valuation for company-specific risks.
This approach produces a valuation grounded in the company’s financial performance, growth expectations, and comparable market evidence, rather than a generic SaaS revenue multiple.
Why Similar SaaS Companies Receive Different Valuations
Two SaaS companies with similar revenue can have substantially different valuations, even when they operate in the same market. The difference often comes down to their financial performance, growth expectations, and business risks.
Several factors help explain these differences:
Revenue growth: How quickly the business is expanding and whether its historical performance supports future growth assumptions.
Customer retention: How much recurring revenue the company retains and expands within its existing customer base.
Gross margins: How efficiently the company delivers its software and supports customers.
Customer acquisition efficiency: How much capital is required to acquire new customers and generate additional recurring revenue.
Profitability: Whether the company can translate revenue growth into sustainable earnings and cash flow.
Revenue concentration: How dependent the business is on individual customers or contracts.
At Finro, we examine these factors to evaluate the company’s financial projections, identify potential risks, and determine appropriate valuation adjustments. Strong historical performance can help support an ambitious forecast, while weak retention, inefficient customer acquisition, or high customer concentration may raise questions about its reliability.
The following sections explain the valuation methods, how we build comparable-company benchmarks, and how these financial characteristics contribute to the final valuation.
How a $15 million enterprise valuation translates into the value attributable to shareholders.
Applying EV/Revenue or EV/EBITDA multiples produces an enterprise value estimate, not an equity value. To estimate the value attributable to shareholders, enterprise value must be adjusted for debt, cash, and other relevant items. Actual transaction proceeds may also depend on the company's capitalization table and deal terms.
Illustrative calculation. Assumes no additional enterprise-to-equity adjustments.SaaS Valuation Methods
There are several ways to value a SaaS company, but not every method is equally relevant to every business.
For a SaaS startup generating recurring revenue but still operating at a loss, revenue-based multiples can provide a useful starting point. For a mature software company with consistent profitability, EBITDA multiples and discounted cash flow analysis may offer a better indication of its value.
At Finro, we generally examine more than one valuation methodology, using historical financial performance as the baseline for evaluating the company’s projections. For early-stage SaaS startups, our approach typically combines market-derived valuation multiples with weighted financial forecasts, supported by comparable-company analysis and company-specific risk adjustments. Other methods, including DCF, can provide additional perspectives when the underlying assumptions support their use.
For a broader comparison of these approaches and their applicability across funding stages, see Finro’s guide to startup valuation methods.
Revenue Multiple Valuation (EV/Revenue)
Revenue multiples are widely used in SaaS valuations, particularly for companies prioritizing growth over near-term profitability.
The conventional approach estimates enterprise value by applying a market-derived valuation multiple to a company’s annual revenue.
Enterprise Value = Revenue × EV/Revenue Multiple
However, applying a multiple to current revenue alone may not adequately reflect an early-stage SaaS company’s growth potential.
At Finro, we use our Forecast-Weighted Multiples Method, which applies a market-derived EV/Revenue multiple to a weighted average of the company’s projected revenue over five years. Near-term projections receive greater weight, while later years receive progressively lower weights to account for the increasing uncertainty of longer-term forecasts.
Historical and current financial performance remain the foundation of this analysis. They help us evaluate the company’s growth assumptions, assess the credibility of its financial projections, and defend the resulting valuation.
The valuation multiple itself is derived from our Multi-Niche Comps Analysis, which examines comparable companies across the technology niches relevant to the startup’s business model. We use median market multiples as valuation benchmarks rather than relying on a generic SaaS industry average.
Once the preliminary enterprise valuation is calculated, we assess relevant company-specific risks and apply appropriate valuation discounts.
The main advantage of revenue multiples is that they can be applied to SaaS companies that haven’t reached profitability. However, revenue alone doesn’t capture the cost of generating growth, customer retention, or the risks associated with future performance. These factors must be considered when developing the financial projections and assessing the final valuation.
EBITDA Multiple Valuation (EV/EBITDA)
EBITDA multiples become more relevant when a SaaS company has established a reasonably stable level of operating profitability.
EBITDA stands for earnings before interest, taxes, depreciation, and amortization. It is commonly used as a measure of operating earnings, although it is not equivalent to cash flow.
The conventional valuation formula is:
Enterprise Value = EBITDA × EV/EBITDA Multiple
At Finro, we can also apply our Forecast-Weighted Multiples Method to EBITDA, using a weighted average of the company’s projected earnings over five years rather than relying exclusively on historical profitability. As with revenue-based valuations, the selected multiple is derived from comparable-company analysis, while company-specific risks are assessed separately.
In practice, EBITDA-based valuations may require adjustments to reported earnings. One-time expenses, unusual compensation arrangements, and other nonrecurring items may need to be normalized to better reflect the company’s ongoing earning capacity.
This method is less useful for SaaS startups reporting negative EBITDA because of substantial investments in sales, product development, or market expansion. Applying an EBITDA multiple to negative earnings does not produce a meaningful enterprise valuation.
However, profitability shouldn’t be ignored simply because a company is growing. As SaaS businesses mature, their ability to convert recurring revenue into sustainable earnings becomes increasingly important to investors and potential acquirers.
Discounted Cash Flow (DCF) Valuation
Discounted cash flow valuation takes a different approach. Rather than applying a market multiple to a financial metric, DCF estimates the value of a business based on the cash flows it is expected to generate in the future.
For a typical enterprise DCF, projected free cash flows to the firm are discounted using the weighted average cost of capital (WACC). A terminal value accounts for cash flows beyond the explicit forecast period.
The analysis generally requires projections of:
Revenue growth, including customer acquisition, retention, and expansion.
Gross margins and operating expenses.
Taxes and capital expenditures.
Working capital requirements.
Long-term profitability and cash generation.
For SaaS companies, the quality of the revenue forecast is particularly important. At Finro, we use our User Journey Method to build bottom-up revenue projections based on customer acquisition, conversion, retention, expansion, and pricing assumptions. This approach connects projected revenue to the company’s business model and historical performance rather than simply assuming a fixed annual growth rate.
DCF can be useful for both profitable and unprofitable SaaS businesses, provided there is a credible basis for forecasting future cash flows.
The difficulty is that small changes in long-term growth, margins, discount rates, or terminal value assumptions can materially affect the result. For early-stage SaaS companies with limited operating history, these uncertainties can make DCF less reliable than an appropriately constructed comparable-company analysis.
That doesn’t mean DCF should be excluded. It can provide an additional valuation perspective, but the weight assigned to its results should reflect the reliability of the financial projections and the assumptions underlying the model.
Comparable Company Analysis: Public, Private, and M&A Valuations
Revenue and EBITDA multiples are only as useful as the market evidence behind them.
At Finro, we build our Multi-Niche Comps Analysis using three main sources of valuation data:
Publicly traded companies: Their market capitalizations, financial disclosures, and trading data allow us to calculate valuation multiples, primarily EV/Revenue and EV/EBITDA.
M&A transactions: Acquisitions provide evidence of prices paid for businesses operating in relevant markets. However, transaction multiples may reflect strategic premiums, expected synergies, or deal-specific circumstances.
Private companies and funding rounds: Venture financing data provides valuation benchmarks for startups at different stages of development. These valuations require careful interpretation because funding rounds typically report equity valuations, and preferred share rights can affect their comparability.
These sources provide different perspectives on market valuations and shouldn’t be treated as interchangeable.
Rather than selecting a handful of companies that broadly resemble the startup, we begin by breaking down its business model into the technology niches that best represent its products, services, and revenue streams.
For each relevant niche, we typically identify 15–20 comparable companies, including public companies, private startups, and M&A transactions. We then collect the available financial and valuation data to calculate median and average multiples, including EV/Revenue, EV/EBITDA, and EV/Funding where applicable.
The median multiples provide market benchmarks for the valuation, while the broader dataset helps us understand differences between niches, company types, and funding stages.
This approach is particularly relevant for SaaS startups whose business models combine several technologies or serve multiple markets. A generic SaaS industry multiple may overlook important differences between the company’s underlying business activities.
The resulting comparable-company analysis provides the market evidence used in Finro’s Forecast-Weighted Multiples Method. Company-specific financial performance and risks are evaluated separately through the financial projections and subsequent valuation adjustments.
We’ll examine how to select relevant niches, interpret comparable-company data, and establish appropriate valuation benchmarks in the next section.
Revenue multiples, EBITDA multiples, and DCF provide different approaches to estimating enterprise value. Finro supports these methods with financial forecasting and comparable-company analysis.
Valuation MethodsApplies a market-derived revenue multiple to a financial metric. Particularly useful for growing SaaS companies that have not reached profitability.
Applies a market-derived earnings multiple to EBITDA. More relevant for companies with sustainable operating profitability or credible earnings forecasts.
Estimates enterprise value from projected future cash flows, discounted to present value. Highly dependent on forecast assumptions and long-term profitability.
Historical and current financial performance establish the baseline for the analysis. Three complementary components help us develop forecasts, establish market benchmarks, and calculate defensible valuations.
Builds bottom-up revenue forecasts using customer acquisition, conversion, retention, expansion, and pricing assumptions. Supports both multiples-based valuations and DCF cash flow projections.
Examines public companies, private startups, and M&A transactions across relevant technology niches to establish market multiples and supporting valuation evidence.
Applies selected market multiples to weighted five-year revenue or EBITDA projections, followed by relevant company-specific valuation adjustments.
Finro's analytical components support the valuation methods rather than replace them. Market multiples and DCF results are evaluated according to the company's financial profile, forecast reliability, and available market evidence. Different valuation methods do not necessarily receive equal weight.
SaaS Valuation Multiples: How to Select the Right Benchmark
Finding an average SaaS valuation multiple is relatively easy. Finding one that actually applies to a specific company is considerably harder.
SaaS valuation multiples vary depending on company size, growth, profitability, customer retention, and market conditions. They also differ between publicly traded companies, private funding rounds, and M&A transactions.
At Finro, we use our Multi-Niche Comps Analysis to establish market valuation benchmarks. Rather than treating SaaS as a single industry, we break down the company’s business model into its underlying technology niches and examine comparable companies within each one.
This approach allows us to identify valuation differences between the markets a SaaS startup operates in, rather than relying on a broad industry average that may not accurately represent its business.
How to Interpret SaaS Valuation Multiples
SaaS valuation multiples provide a way to compare companies with different financial profiles, but not every multiple measures the same thing.
At Finro, we examine three main valuation benchmarks:
EV/Revenue: Compares enterprise value with annual revenue. Particularly relevant for growing SaaS companies that have not yet reached profitability.
EV/EBITDA: Compares enterprise value with operating earnings before interest, taxes, depreciation, and amortization. Generally more informative for businesses with established or reasonably predictable profitability.
EV/Funding: Compares enterprise value with the total funding raised by a company. We use this as a supplementary benchmark when analyzing private startups, particularly where operating financial information is limited.
The availability and reliability of these multiples depend on the financial information disclosed by comparable companies.
For public companies, revenue and EBITDA data are generally accessible through financial reporting. For private startups, funding information may be more readily available than operating financials, although reported equity valuations must be distinguished from enterprise values.
It’s also important to use consistent financial metrics when comparing companies. Historical revenue multiples, forward revenue multiples, and funding-based benchmarks represent different relationships and shouldn’t be treated as interchangeable.
Rather than relying on a single observation, we calculate median and average multiples across the relevant comparable-company datasets. The median provides a useful market benchmark by reducing the influence of unusually high or low valuations.
Public SaaS Trading Multiples
Publicly traded SaaS companies provide one of the most accessible sources of valuation benchmarks.
Their enterprise values can be estimated using publicly available market data, while financial disclosures provide information about revenue, profitability, growth, and other operating metrics.
However, public SaaS companies are often substantially larger and more established than the startups being valued.
They may benefit from greater revenue diversification, stronger market positions, easier access to capital, and more predictable financial performance.
For that reason, public trading multiples should be treated as market evidence rather than directly transferable valuations.
A Seed-stage SaaS startup generating $500,000 in annual revenue should not automatically receive the same valuation as a publicly traded software company generating $500 million. Public trading multiples provide market benchmarks, but the startup’s projected performance and company-specific risks must be evaluated separately.
Private SaaS Valuation Multiples
Private SaaS companies present a different challenge because their financial information and transaction terms are rarely as transparent as those of public companies.
Funding announcements often disclose the amount raised and sometimes a headline valuation. However, they may not provide sufficient revenue data to calculate a reliable valuation multiple.
Even when both figures are available, the financing structure matters.
A venture capital round typically establishes a negotiated equity valuation, often involving preferred shares with rights that differ from those of common shareholders. That valuation is not automatically equivalent to the enterprise value used in public trading multiples.
When analyzing private SaaS valuations, we therefore examine the funding stage, business maturity, available financial metrics, and financing terms before treating a transaction as a relevant benchmark.
When reliable enterprise value and funding information are available, we also calculate EV/Funding multiples to provide an additional benchmark for private startup valuations. These funding-based multiples complement the revenue and EBITDA analysis rather than replace it.
SaaS M&A Valuation Multiples
M&A transactions offer another important source of market evidence, particularly when valuing a SaaS company for a potential acquisition.
Unlike public trading multiples, acquisition multiples reflect prices negotiated between buyers and sellers.
These prices may incorporate factors that are specific to the transaction, including strategic synergies, customer relationships, intellectual property, competitive positioning, and the buyer’s expectations for integrating the acquired business.
A strategic acquirer may be willing to pay a premium for a SaaS company whose technology or customer base complements its existing operations. A financial buyer may place greater emphasis on recurring cash flows, operational efficiency, and opportunities to improve profitability.
Consequently, an acquisition multiple should not be interpreted without understanding the transaction behind it.
At Finro, M&A transactions form part of our Multi-Niche Comps Analysis, providing additional market evidence alongside public trading multiples and private startup valuations.
How to Select Comparable SaaS Companies
A SaaS startup rarely fits perfectly into a single industry category.
Consider a company offering an AI-powered cybersecurity platform. Its business model may combine cybersecurity software, AI infrastructure, and enterprise SaaS. Comparing it exclusively with traditional cybersecurity companies could overlook important aspects of its technology and revenue model.
At Finro, we address this challenge through our Multi-Niche Comps Analysis.
The process begins by identifying the technology niches that best represent the company’s products, services, and business model.
For each relevant niche, we typically identify 15–20 comparable companies, drawing from publicly traded businesses, private startups, and M&A transactions.
We then collect the available financial and valuation data, including enterprise value, revenue, EBITDA, funding raised, funding stage, and transaction information.
The analysis considers several factors when evaluating the relevance of individual comparables:
Business model: Subscription-based, usage-based, hybrid SaaS, or software businesses with substantial services revenue.
Customer segment: SMB, mid-market, enterprise, or a combination of these markets.
Growth and profitability: Revenue growth, gross margins, EBITDA margins, and operating efficiency.
Revenue quality: Customer retention, recurring revenue concentration, and contractual visibility.
Scale and maturity: Revenue size, funding stage, operating history, and geographic exposure.
Once the comparable-company datasets are established, we calculate median and average EV/Revenue and EV/EBITDA multiples for each niche. We also examine EV/Funding ratios where sufficient information is available, using them as supplementary reference points rather than inputs to the valuation calculation.
We generally use median market multiples as the primary valuation benchmarks because they reduce the influence of unusually high or low observations.
The resulting analysis provides a market-based foundation for the valuation. We then use the relevant multiples within our Forecast-Weighted Multiples Method, applying them to projected financial performance before assessing company-specific valuation risks.
This approach allows us to evaluate a SaaS company across the different technology markets that contribute to its business model, rather than forcing it into a single industry category.
Rather than applying a generic SaaS industry multiple, we analyze the technology niches underlying a company's business model to establish market-based valuation benchmarks.
Break down the company's business model into relevant technology categories based on its products, services, and target markets.
Identify approximately 15–20 comparable companies per niche, including public businesses, private startups, and M&A transactions.
Calculate median and average EV/Revenue and EV/EBITDA multiples where financial data is available. Review EV/Funding separately as a reference metric.
Evaluate niche-level median multiples and the underlying market evidence to establish benchmarks for the company's valuation.
Trading valuations and reported financial performance.
Funding rounds, disclosed valuations, and available operating metrics.
Acquisition valuations and transaction-specific financial data.
Different technology niches can have substantially different valuation characteristics. Finro uses niche-specific median multiples to establish market benchmarks, rather than applying a generic SaaS industry average. Company-specific risks are assessed separately when calculating the final valuation.
What Drives SaaS Valuation?
Two SaaS companies can generate identical annual recurring revenue and still receive very different valuations. The difference usually comes down to how much growth investors expect, how efficiently that growth is generated, and how predictable the company’s future revenue and profitability appear.
While market-derived multiples provide the valuation benchmarks, a company’s financial and operational performance helps determine the credibility of its projections and the risks associated with achieving them. At Finro, these factors influence the financial forecasts and company-specific valuation adjustments rather than automatically changing the selected market multiple.
Revenue Growth and ARR
Revenue growth is one of the most influential factors in SaaS valuation, particularly for early-stage companies.
Investors look beyond the current ARR figure to understand how quickly the business is expanding and whether that growth can continue.
A company growing ARR by 60% annually will generally attract different valuation expectations from one growing at 10%, assuming other financial characteristics are comparable.
However, growth rates need context. A startup doubling revenue from $200,000 to $400,000 ARR is not necessarily comparable to a company growing from $20 million to $40 million.
Growth should also be evaluated alongside the cost of acquiring customers and the company’s ability to retain them.
Customer Retention and Net Revenue Retention (NRR)
Recurring revenue is valuable because customers are expected to continue paying for the software. That expectation becomes less convincing when churn is high.
Two metrics are particularly relevant:
Gross Revenue Retention (GRR) measures how much recurring revenue is retained from existing customers, excluding expansion revenue.
Net Revenue Retention (NRR) measures recurring revenue retained from existing customers after accounting for churn, contraction, and expansion.
An NRR above 100% indicates that expansion revenue from existing customers exceeds the revenue lost through churn and contraction.
For example, a SaaS company with 115% NRR generates 15% more recurring revenue from its starting customer cohort, even before adding new customers.
Strong retention supports more predictable revenue forecasts and reduces the company’s dependence on acquiring new customers to sustain growth. It can also reduce the risks associated with achieving projected financial performance.
However, NRR should be interpreted alongside customer concentration and the composition of expansion revenue. A few large customers increasing their spending can sometimes mask weaker retention across the broader customer base.
Gross Margins and Revenue Quality
SaaS companies are often associated with high gross margins, but actual margins vary considerably across business models.
Traditional subscription software may have a different cost structure from AI-powered SaaS, infrastructure software, or platforms with substantial hosting, implementation, and customer support costs.
Gross margin matters because it indicates how much revenue remains after the direct costs of delivering the product.
A company generating $5 million in annual revenue at an 85% gross margin has a different economic profile from one generating the same revenue at a 55% margin.
Revenue composition also matters. Investors typically distinguish between predictable subscription revenue, variable usage-based revenue, and nonrecurring professional services.
These revenue streams may have different margins, retention characteristics, and levels of predictability, all of which influence valuation.
Customer Acquisition Cost and LTV/CAC
Growth becomes less attractive when acquiring additional customers requires disproportionate spending.
Customer acquisition cost (CAC) measures the cost of acquiring a new customer, while customer lifetime value (LTV) estimates the gross profit expected from that customer over the relationship.
The LTV/CAC ratio compares the economic value of customers with the cost of acquiring them.
Another useful metric is CAC payback period, which estimates how long it takes to recover customer acquisition costs through customer gross profit.
For valuation purposes, these metrics help assess whether the company can scale efficiently.
However, LTV estimates depend heavily on assumptions about churn, customer lifetime, and future margins. For young SaaS companies with limited retention history, CAC payback and observed cohort performance may provide more reliable evidence than an aggressive lifetime value estimate.
Profitability and the Rule of 40
As SaaS companies mature, investors increasingly examine the relationship between growth and profitability.
The Rule of 40 is a commonly used benchmark that combines revenue growth and profitability into a single measure:
Rule of 40 = Revenue Growth Rate + Profit Margin
For example, a SaaS company growing revenue by 30% with a 15% EBITDA margin would achieve a Rule of 40 score of 45%.
The metric is useful for comparing companies pursuing different growth and profitability strategies. However, the chosen profitability measure must be consistent across the companies being compared.
The Rule of 40 is not a valuation formula. A score above 40% does not automatically justify a particular revenue multiple, nor does a lower score necessarily indicate that a business is undervalued.
Its value lies in providing additional context for the balance between growth and operating efficiency.
Customer Concentration and Business Risk
Financial performance is only part of the valuation. Investors and acquirers also assess the risks associated with sustaining that performance.
Customer concentration is a particularly important consideration.
A SaaS company generating 40% of its revenue from one enterprise customer may face substantially greater revenue risk than a business with the same ARR distributed across hundreds of customers.
Other relevant risks include:
Dependence on a small number of distribution partners or technology providers.
Short contract durations or limited revenue visibility.
High customer churn or declining product engagement.
Competitive pressure and limited product differentiation.
Regulatory exposure, cybersecurity risks, or technical dependencies.
These risks influence how we evaluate the company’s financial projections and the likelihood of achieving its forecast performance. Some may already be reflected in the assumptions underlying the financial model, while others may warrant additional company-specific valuation adjustments.
At Finro, we assess these risks after establishing the preliminary enterprise valuation using market-derived multiples and weighted financial projections. This separates the market evidence supporting the valuation multiple from the risks associated with the company being valued.
Financial and operational metrics help validate revenue and profitability forecasts, assess business risks, and determine how market valuation benchmarks translate into enterprise value.
These six drivers help us evaluate historical performance, develop and validate financial projections, and identify company-specific risks. Market valuation multiples are established separately through our Multi-Niche Comps Analysis. We then apply those multiples to forecast-weighted financial metrics and assess any additional risk adjustments, avoiding double-counting risks already reflected in the projections.
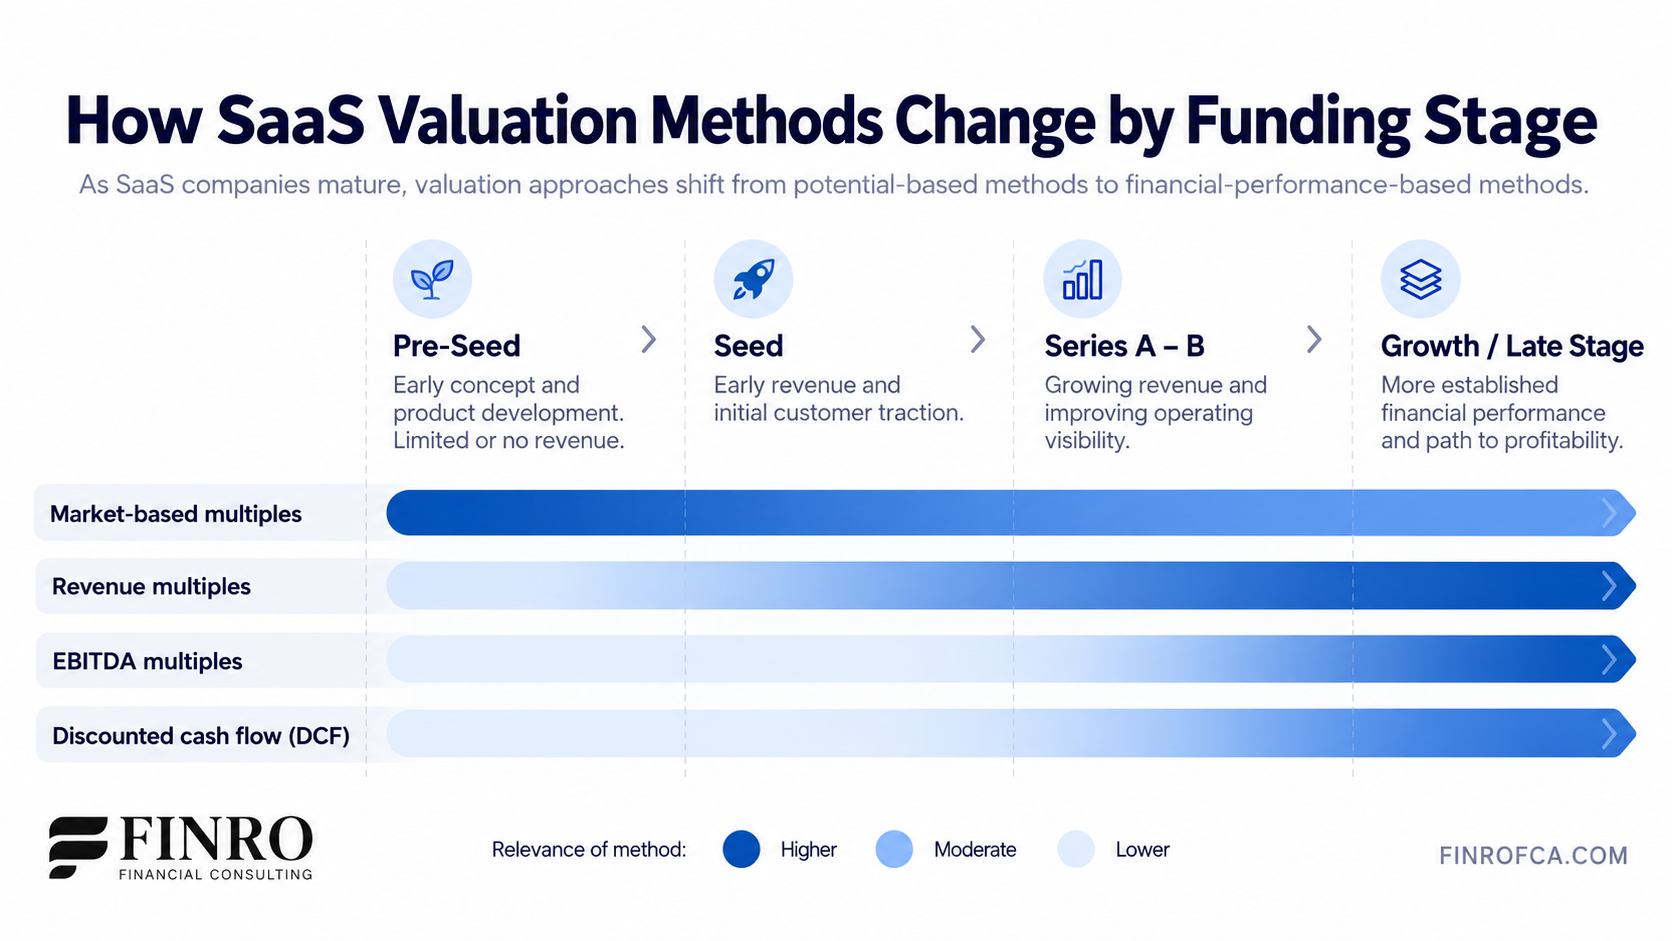
SaaS Valuation by Funding Stage
A SaaS startup’s funding stage influences how its valuation is assessed, primarily because the amount and reliability of available financial information change as the business matures.
A pre-revenue startup may have little operating history to support its projections, while a Series B company may have several years of revenue, customer retention, and profitability data.
The underlying valuation methods do not necessarily change between these stages. However, the financial assumptions, available comparable-company data, and risks associated with future performance can differ substantially.
At Finro, we adapt the valuation analysis to the company’s maturity, using historical performance where available, forward-looking financial projections, and market evidence from relevant technology niches.
Pre-Seed SaaS Valuation
Pre-seed SaaS companies are typically developing their products, validating market demand, or working toward their first paying customers.
At this stage, historical revenue may be limited or nonexistent, making conventional revenue and EBITDA multiples difficult to apply directly to current financial performance.
Valuation therefore depends heavily on the company’s expected commercial development, including its target market, pricing strategy, customer acquisition assumptions, and ability to convert early interest into recurring revenue.
At Finro, we use our User Journey Method to develop bottom-up financial projections based on expected customer acquisition, conversion rates, retention, and monetization.
These projections can support a forecast-weighted revenue multiple valuation, using market benchmarks derived from comparable companies operating in relevant technology niches.
However, the uncertainty associated with early commercial assumptions must be reflected in the valuation assessment.
For pre-revenue companies, DCF may also be considered, but its reliability is often limited by the absence of operating history and the sensitivity of long-term cash flow projections.
Seed-Stage SaaS Valuation
Seed-stage SaaS companies typically have an initial product in the market and may be generating recurring revenue from early customers.
This provides additional evidence for evaluating the business model, although the available operating history may still be too limited to establish reliable long-term trends.
At this stage, valuation analysis increasingly focuses on whether the company can turn early commercial traction into sustainable growth.
Relevant indicators include customer acquisition, ARR growth, churn, pricing validation, and the economics of serving and retaining customers.
A SaaS startup generating $300,000 in ARR may have promising early traction, but its valuation will depend heavily on whether the assumptions supporting its future growth are credible.
We use the available historical data to validate the financial model and assess how customer acquisition, retention, and operating expenses are expected to develop over the forecast period.
Market-derived EV/Revenue multiples can then be applied to forecast-weighted revenue projections, followed by an assessment of company-specific risks.
Seed-stage funding rounds also provide useful market context. However, a disclosed pre-money or post-money equity valuation should not automatically be treated as enterprise value or converted into an EV/Revenue multiple without the necessary adjustments and financial information.
Series A SaaS Valuation
By Series A, SaaS companies are generally expected to demonstrate stronger evidence of product-market fit and a repeatable customer acquisition process.
Revenue growth remains important, but investors increasingly examine the efficiency and sustainability of that growth.
Customer retention, NRR, gross margins, CAC payback, and sales efficiency become more meaningful as the company accumulates operating data.
This additional information allows financial projections to be grounded more firmly in historical performance rather than relying predominantly on initial commercial assumptions.
At Finro, we use this operating history to evaluate the credibility of projected revenue growth, customer retention, and future profitability.
Revenue multiples typically remain relevant, particularly when the company is investing heavily in growth and has not yet achieved sustainable EBITDA.
DCF can also provide a useful additional perspective when the company’s operating history and financial projections support a credible assessment of future cash flows.
Series B and Later-Stage SaaS Valuation
By Series B and subsequent funding rounds, SaaS companies often have more established revenue streams, larger customer bases, and a longer record of financial performance.
The valuation analysis can therefore place greater emphasis on demonstrated growth, revenue quality, operating efficiency, and the company’s path toward sustainable profitability.
Historical financial statements, customer cohorts, gross margin trends, and operating expenses provide a stronger foundation for forecasting future performance.
EV/Revenue multiples remain relevant, but EV/EBITDA becomes increasingly useful when the company has positive or sufficiently predictable earnings.
DCF may also become more informative as the business develops a more reliable basis for forecasting cash flows and estimating long-term financial performance.
However, a later funding stage does not automatically make a SaaS company less risky. Customer concentration, competitive pressure, technology dependencies, and aggressive growth assumptions can remain material valuation considerations.
The objective is to determine which financial metrics and valuation methods are supported by the available evidence, rather than assigning a predetermined multiple or valuation premium based on funding stage alone.
As SaaS companies mature, the valuation analysis can rely increasingly on historical financial performance and observed customer behavior.
Limited or no historical revenue. Early product development and initial market validation.
Customer acquisition assumptions, monetization, and projected commercial development.
Early ARR, initial customer cohorts, and preliminary unit economics.
Validation of growth assumptions, customer retention, and acquisition efficiency.
Established revenue growth, retention history, and operating performance data.
Growth efficiency, recurring revenue quality, and the reliability of financial forecasts.
Longer financial history, established customer cohorts, and clearer profitability trends.
Revenue sustainability, earnings potential, cash flows, and operating risks.
Illustrative progression. The amount and reliability of financial evidence vary between companies, regardless of funding stage.
Funding stage influences the available financial evidence, not the valuation formula itself. Finro uses market-derived multiples and financial projections across funding stages, incorporating DCF and EBITDA-based valuations when the company's financial performance supports their use. Company-specific risks are assessed separately.
SaaS Business Valuation Example
How much is a SaaS startup worth if it generates recurring revenue but has not yet reached profitability?
Let’s consider a hypothetical B2B SaaS company that provides workflow automation software to enterprise customers.
The company generates approximately $1 million in annual revenue, has an established customer base, and expects significant growth over the next five years. However, it remains unprofitable as it continues investing in product development and customer acquisition.
We’ll use this example to illustrate how Finro approaches SaaS business valuation, from financial forecasting to comparable-company analysis and the final valuation assessment.
Step 1: Build a Credible Revenue Forecast
The starting point is understanding how the company generates revenue and whether its growth expectations are realistic.
At Finro, we use our User Journey Method to develop revenue projections based on the underlying business activities that drive customer acquisition, conversion, retention, and monetization.
Rather than applying arbitrary annual growth rates, we examine the commercial assumptions required to support the company’s financial projections.
Historical financial and operating performance provides the baseline for this analysis, helping us evaluate whether the projected growth is consistent with the company’s actual performance and commercial capabilities.
The following framework illustrates how our approach differs from conventional top-down revenue forecasting.
Top-down assumptions can support high-level planning. A bottom-up forecast goes further by connecting projected revenue to the customer activity and commercial assumptions required to achieve it.
- Year 1 Revenue
- +60% growth
- Year 2 Revenue
- +65% growth
- Year 3 Revenue
- Monthly budget Channel allocation
- Clicks Cost per click
- Trial / Demo Visitor-to-trial conversion %
- Sign-up Trial-to-paid conversion %
- Subscription revenue Pricing assumptions
- ARR / MRR Retention & expansion
Finro's User Journey Method connects financial projections to measurable business activities, providing a more defensible foundation for revenue-based valuations and, where appropriate, DCF analysis.
For our hypothetical SaaS company, the resulting forecast projects annual revenue increasing from approximately $1 million to $5 million over the next five years.
These projections provide the financial foundation for the valuation. However, projected revenue alone does not determine what the company is worth.
Step 2: Establish Relevant Market Valuation Benchmarks
Next, we examine how comparable SaaS businesses are valued in the market.
Finro uses its Multi-Niche Comps Analysis to identify relevant companies across the technology segments that best represent the target company’s business model.
For our hypothetical company, the analysis might include enterprise software, workflow automation, and other relevant B2B SaaS niches.
We typically examine 15–20 companies per niche, drawing on available financial information from public companies, private funding rounds, and M&A transactions.
The objective is to establish defensible market benchmarks rather than relying on a broad SaaS industry average.
For this example, assume our comparable-company analysis supports an illustrative EV/Revenue multiple of 8.0x.
This is a hypothetical multiple used to demonstrate the valuation process, not a current market benchmark.
Step 3: Assess Financial Performance and Company-Specific Risks
Market multiples provide a valuation benchmark, but they do not automatically determine the value of an individual SaaS company.
We also need to assess the credibility of its financial projections, the quality of its recurring revenue, and the risks associated with achieving its business plan.
For our hypothetical company, several factors could influence the valuation:
Revenue growth supported by customer acquisition and retention assumptions.
Recurring revenue quality, including customer concentration and churn.
Customer acquisition costs and the company’s ability to scale efficiently.
Gross margins and the expected path toward profitability.
Execution risks associated with enterprise sales cycles and future expansion.
Finro’s Forecast-Weighted Multiples Method incorporates projected financial performance, assigning greater importance to nearer-term forecasts.
We then evaluate company-specific risks and apply any appropriate adjustments to the preliminary enterprise valuation, taking care not to duplicate risks already reflected in the financial model.
The result is a valuation assessment grounded in both market evidence and the company’s expected financial performance.
Step 4: Determine the SaaS Enterprise Valuation
After evaluating the company’s financial projections, comparable-company benchmarks, and risk profile, we can establish an indicative enterprise valuation.
For our hypothetical SaaS company, assume the analysis supports an illustrative enterprise valuation range of $9 million to $12 million.
This range reflects the company’s growth prospects, recurring revenue characteristics, relevant market benchmarks, and uncertainty surrounding its financial projections.
It is not calculated by simply multiplying the company’s current $1 million revenue by the selected 8.0x market multiple.
Instead, the assessment considers the company’s expected financial performance over the forecast period, supported by comparable-company evidence and adjusted for company-specific risks.
The resulting enterprise valuation is also distinct from equity value. The value attributable to shareholders would require consideration of the company’s cash, debt, and relevant capital structure.
What This SaaS Valuation Example Demonstrates
A SaaS company’s valuation depends on more than its current ARR or the average revenue multiple of publicly traded software companies.
Two startups generating the same annual revenue may receive substantially different valuations because of differences in customer retention, revenue quality, growth expectations, profitability, and business risk.
Our hypothetical company illustrates how financial forecasting, market evidence, and professional judgment contribute to a defensible valuation conclusion.
Depending on the company’s financial maturity, Finro may also use EV/EBITDA multiples or a Discounted Cash Flow analysis to provide additional valuation perspectives.
Valuing a Growing B2B SaaS Company
How financial projections, market benchmarks, and company-specific risks contribute to an enterprise valuation assessment.
Revenue projections built around customer acquisition, conversion, retention, and pricing assumptions, informed by historical performance.
User Journey MethodEV/Revenue benchmarks derived from comparable public companies, private funding rounds, and M&A transactions.
Illustrative Multiple: 8.0xEvaluation of revenue quality, customer concentration, operating efficiency, forecast reliability, and execution risks.
Risk-Adjusted Enterprise ValuationSaaS valuations are not determined by applying an industry-average multiple to current revenue. They reflect projected financial performance, relevant market evidence, and company-specific risks.
Hypothetical example for educational purposes. Revenue projections, valuation multiples, and enterprise valuation ranges are illustrative and do not represent current market benchmarks or a valuation opinion for an actual company.
Common SaaS Valuation Mistakes
SaaS valuations can look convincing on paper while relying on assumptions that are difficult to defend. A sophisticated financial model or an impressive revenue multiple doesn’t necessarily mean the underlying valuation is reliable.
At Finro, we regularly encounter several mistakes when reviewing startup valuations and financial models:
Using generic SaaS valuation multiples. Applying broad industry averages without considering differences in business models, growth rates, profitability, or funding stages. Relevant comparable companies provide a more defensible benchmark.
Relying on unsupported revenue projections. Forecasting aggressive growth without connecting it to customer acquisition, conversion, retention, and pricing assumptions. Historical performance and measurable business drivers should support the projections.
Confusing enterprise value with equity value. Treating enterprise valuation, funding-round equity valuation, and shareholder value as interchangeable, without considering cash, debt, and relevant capitalization terms.
Ignoring revenue quality and business risks. Focusing on ARR while overlooking churn, customer concentration, gross margins, operating efficiency, and execution risks that can materially affect valuation.
Trusting automated valuation outputs without reviewing the assumptions. Accepting a valuation report without understanding its comparable companies, financial projections, methodology, or risk assessment. A calculated figure is not necessarily a defensible valuation.
These mistakes have one thing in common: they reduce valuation to a number rather than an analysis of the business.
A credible SaaS valuation should connect financial performance, future expectations, market evidence, and company-specific risks into a conclusion that can withstand investor scrutiny.
When Should You Get a Professional SaaS Valuation?
Not every SaaS startup needs a comprehensive valuation report. For early-stage founders exploring different growth scenarios or preparing an internal budget, a preliminary valuation estimate may be sufficient.
However, certain situations require a more detailed analysis that can withstand scrutiny from investors, board members, or potential acquirers.
A professional SaaS valuation is particularly relevant when:
Raising capital. Founders need to establish and defend their company’s valuation during fundraising negotiations, particularly when the business has limited financial history or operates across multiple technology niches.
Preparing for an acquisition or exit. Buyers and sellers need an independent assessment of enterprise value, supported by financial projections, relevant comparable transactions, and company-specific risk considerations.
Evaluating secondary share transactions. Existing shareholders, employees, or early investors may need a valuation to support discussions about selling equity or transferring ownership.
Supporting board and shareholder decisions. Management teams may require an independent valuation when evaluating strategic alternatives, capital structure changes, or significant corporate transactions.
Validating an existing valuation. Founders who have already prepared a valuation internally or through automated software may benefit from an independent review of their assumptions, market benchmarks, and conclusions.
The value of a professional SaaS valuation goes beyond producing a number. It provides a structured financial analysis that explains how the company’s performance, growth expectations, market positioning, and risks contribute to its enterprise value.
At Finro, we combine bottom-up financial modeling, multi-niche comparable-company analysis, and company-specific risk assessments to develop valuations tailored to each SaaS company’s business model and funding stage.
Once a professional valuation becomes necessary, the next step is preparing the information needed to assess the company’s financial performance, growth potential, and risk profile.
SaaS Valuation Is More Than a Revenue Multiple
A SaaS company's valuation cannot be reduced to its ARR multiplied by an industry benchmark. Two companies generating identical revenue can have significantly different valuations depending on their growth potential, customer retention, profitability, market positioning, and execution risks.
At Finro, we approach SaaS valuation by connecting historical financial performance with bottom-up projections, relevant market comparables, and company-specific risk assessments. The objective isn't simply to calculate an enterprise value, but to establish a valuation that founders, investors, and potential acquirers can understand, evaluate, and defend.
- SaaS valuation depends on more than recurring revenue. Growth expectations, retention, profitability, revenue quality, and execution risks can materially affect the value of companies with similar ARR.
- Valuation multiples must reflect the company's business model. Generic SaaS benchmarks can be misleading. Relevant public companies, private funding rounds, and M&A transactions provide a stronger foundation for comparable-company analysis when their valuation measures are interpreted consistently.
- Financial projections should be grounded in business activity. Historical performance provides the baseline, while customer acquisition, conversion, retention, pricing, and expansion assumptions support the revenue forecast.
- The appropriate valuation method depends on the company's maturity. Revenue multiples are often relevant for growing SaaS startups, while EBITDA multiples and discounted cash flow analysis may become more informative as profitability and cash flow visibility improve.
- A defensible valuation connects market evidence with company-specific analysis. Financial forecasts, relevant comparable companies, and risk assessments should support a coherent enterprise valuation rather than an isolated calculation.