Aeron Sullivan
Founder and CEO, Pangea.io
Valuing a fintech startup requires more than applying a revenue multiple to its financial projections. A payment processor, digital lender, and fintech infrastructure provider may operate in the same industry, but their revenue models, cost structures, and risk profiles can be fundamentally different. These differences have a direct impact on how each company should be valued.
At Finro, we provide independent fintech startup valuation services for founders, investors, and companies preparing for fundraising, M&A transactions, and strategic investment decisions. Our approach combines financial modeling, discounted cash flow (DCF) analysis, comparable-company benchmarking, and transaction multiples to develop valuations grounded in each company’s business model and financial performance.
Drawing on our fintech valuation research covering public companies, private startups, and M&A transactions, we evaluate the assumptions driving a company’s valuation, from revenue growth and unit economics to profitability, capital requirements, and market positioning.
This article explains how we approach fintech startup valuations, the financial considerations that influence our analysis, and what founders and investors can expect from a valuation engagement with Finro.
A fintech startup’s valuation becomes particularly important when founders, investors, or shareholders need to make decisions involving equity, capital, or ownership. While valuation is often associated with fundraising, there are several situations where an independent financial assessment can help establish a defensible company value.
Whether raising a Seed round or preparing for Series B, fintech founders need to support their valuation expectations with financial projections, relevant market benchmarks, and realistic growth assumptions. An independent valuation can help establish a reasonable valuation range and provide a financial basis for investor discussions.
Fintech M&A transactions require a detailed assessment of the target company’s financial performance, growth potential, and risk exposure. Buyers and sellers may have different expectations regarding future revenue, profitability, and strategic value. A professional valuation helps establish a financial reference point for negotiations and evaluate whether a proposed transaction price is reasonable.
Secondary share sales, shareholder buyouts, and changes in ownership may require an independent assessment of company value. This is particularly relevant for private fintech startups where publicly observable share prices are unavailable and recent funding rounds may not reflect current financial performance.
Fintech companies may also require valuations when evaluating financing alternatives, restructuring their operations, or assessing strategic opportunities. In these situations, valuation analysis can help management understand how different growth assumptions, capital requirements, and financial risks influence the company’s value.
Fintech is not a single business model. A payment processor generating revenue from transaction fees has little in common financially with a digital lender earning interest income or a fintech infrastructure company selling API subscriptions. Yet these businesses are frequently grouped under the same industry classification when comparing valuations.
This creates a challenge for fintech startup valuation. Companies with similar revenue and growth rates may have substantially different profitability, capital requirements, and risk exposure. Applying the same revenue multiple across these businesses can therefore produce misleading results.
At Finro, we examine the underlying economics of each fintech business model before selecting valuation methodologies and comparable companies. Several financial considerations are particularly important.
For payment processors and remittance platforms, transaction volume is not equivalent to revenue. Take rates, processing fees, interchange arrangements, and the distinction between gross and net revenue can significantly affect reported financial performance.
A company processing $500 million annually with a 1% net revenue yield generates very different economics from a platform earning a 3% yield on the same volume. Understanding how much revenue the company actually retains is essential when evaluating financial projections and market multiples.
Lending platforms and certain digital banking businesses face financial risks that are less relevant to software-based fintech companies. Loan defaults, funding costs, regulatory capital requirements, and credit portfolio quality can materially influence profitability and shareholder value.
These differences also affect methodology selection. While EV/Revenue multiples may be appropriate for certain fintech software businesses, equity-based valuation approaches and financial institution benchmarks may be more relevant for lenders retaining substantial credit exposure.
Customer acquisition costs, retention, and monetization vary considerably across fintech niches. A WealthTech platform may generate recurring fees based on assets under management, while a payments company depends on transaction activity and take rates.
Fintech infrastructure providers may have subscription-based or usage-based revenue models, but their valuations still depend on factors such as customer concentration, gross margins, revenue retention, and integration costs.
These differences make comparable-company selection particularly important. A high-growth payments business should not automatically be valued using multiples from lending platforms or SaaS companies simply because they operate within fintech.
Finro’s approach considers business model similarity, revenue composition, growth, profitability, and risk exposure when identifying relevant public companies, private funding rounds, and M&A transactions. The objective is to establish valuation benchmarks that reflect the company’s actual financial characteristics rather than relying on broad fintech industry averages.
Fintech companies require different valuation assumptions depending on how they generate revenue, manage risk, and finance their operations.
Transaction volume, net take rates, processing margins, and customer concentration.
Customer monetization, deposit economics, regulatory capital, and funding structure.
Loan portfolio quality, credit losses, funding costs, and balance-sheet exposure.
Assets under management, recurring fees, net inflows, and customer retention.
Recurring revenue, API usage, gross margins, and customer revenue retention.
Source: Finro Financial Consulting. Illustrative valuation considerations; methodology selection depends on each company's business model and financial characteristics.
At Finro, we don’t apply a single valuation formula to every fintech company. Our approach starts with understanding the company’s business model, financial performance, growth assumptions, and risk exposure. We then select valuation methodologies that reflect its operating economics and stage of development.
Depending on the company’s financial structure and the purpose of the engagement, we typically combine financial modeling, market-based valuation methods, and discounted cash flow analysis to establish a supportable valuation range.
A valuation is only as reliable as the financial assumptions supporting it. We review the company’s existing financial model, assess its revenue and cost projections, and evaluate whether the assumptions reflect its actual business economics.
For payments businesses, this may involve examining transaction volumes, take rates, processing costs, and customer retention. For lending platforms, we focus on loan originations, credit losses, funding costs, and capital requirements. Subscription-based fintech companies require a different analysis, including recurring revenue, customer acquisition costs, churn, and operating leverage.
When necessary, we develop alternative scenarios to assess how changes in growth, profitability, or funding requirements affect the company’s valuation.
Market-based valuation provides an important reference point, particularly for early-stage fintech companies with limited operating histories or negative cash flows.
Finro identifies relevant publicly traded companies, private funding rounds, and M&A transactions based on business model similarity, financial characteristics, and growth profiles.
Rather than applying a broad fintech industry multiple, we evaluate differences in revenue composition, profitability, market positioning, and risk exposure. Depending on the company, this may involve EV/Revenue, EV/EBITDA, or other appropriate valuation benchmarks.
Private funding rounds and acquisition transactions are evaluated separately, taking into account differences in transaction structure, financing terms, and valuation dates.
Our comparable-company analysis starts with the company's actual business activities, not a broad fintech industry classification. We identify relevant market evidence and evaluate how closely each benchmark reflects the business being valued.
Break down the company's products, revenue streams, and activities into relevant fintech segments.
Research public companies, private funding rounds, and M&A transactions across the selected niches.
Examine revenue models, growth, margins, financial structure, and company-specific risks.
Analyze relevant multiples, assess outliers, and establish supportable market benchmarks.
Banking-as-a-Service and embedded finance infrastructure providers with similar products, customers, and revenue models.
API-based fintech software companies with comparable recurring or usage-based revenue, margins, and growth characteristics.
Relevant funding rounds and acquisitions, evaluated for valuation date, transaction structure, and financial comparability.
We assess the relevance and reliability of each comparable group before selecting valuation benchmarks. Public trading multiples, private funding valuations, and M&A transaction multiples are interpreted separately rather than combined into a single unadjusted average.
Source: Finro Financial Consulting. The embedded finance example illustrates comparable-company selection and does not represent an actual valuation engagement or market-multiple calculation.
DCF analysis estimates a company’s value based on its projected future cash flows and the risks associated with generating them.
For fintech startups, the reliability of a DCF valuation depends heavily on the underlying assumptions. Revenue growth, gross margins, customer economics, operating expenses, and capital requirements can materially influence projected cash flows and terminal value.
We evaluate these assumptions against the company’s operating model and financial outlook. Where appropriate, we incorporate multiple scenarios to reflect uncertainty around growth, profitability, and future financing needs.
For certain regulated financial institutions and balance-sheet lenders, equity-based cash flow approaches may be more appropriate than conventional enterprise DCF models.
Different methodologies can produce substantially different valuation results, particularly for early-stage fintech companies.
A DCF model may indicate significant value based on projected growth, while comparable-company analysis reflects current market pricing and investor expectations.
At Finro, we assess the reliability and relevance of each methodology rather than automatically averaging the results. The weight assigned to each approach depends on factors such as forecast visibility, business maturity, comparable-company availability, and the company’s financial structure.
The objective is to develop a valuation conclusion supported by financial assumptions, relevant market evidence, and a transparent analytical rationale.
We combine company-specific financial analysis with market evidence, then evaluate the reliability of each approach before reaching a valuation conclusion.
Future cash flows, growth assumptions, profitability, and capital requirements.
Public-company multiples, private funding rounds, and relevant M&A transactions.
Forecast reliability, downside exposure, and sensitivity to key financial assumptions.
We assess the relevance and reliability of each methodology and assign appropriate weight to the results. The objective is a valuation conclusion supported by company-specific financial analysis and market evidence, rather than a mechanical average.
Aeron Sullivan
Founder and CEO, Pangea.io
What can I say? Is there a better financial modeling expert for startups than Lior? I doubt it.
Lior is fast, precise, fastidious, and intuitively understands the stage startups are in and what they need in a financial model. I would hire Lior for any FP&A role any day.
I have absolute confidence if you use him for consultant services in the financial space you will not be disappointed.

Market multiples provide an important reference point when valuing fintech startups, but their usefulness depends on selecting the right benchmarks. A revenue multiple derived from a publicly traded payment processor may have limited relevance to an early-stage lending platform or an API-based fintech infrastructure company.
At Finro, we maintain fintech valuation research covering publicly traded companies, private startups, and M&A transactions across different fintech niches. This research helps us identify relevant market benchmarks, evaluate valuation trends, and assess how investors price companies with different business models and financial characteristics.
The appropriate valuation multiple depends on the company’s revenue model, profitability, financial structure, and stage of development.
EV/Revenue is commonly used for high-growth fintech software and payments businesses, particularly when profitability is limited or earnings are not yet representative of the company’s long-term potential. However, differences in gross versus net revenue recognition, processing costs, and revenue quality must be considered before comparing multiples.
EV/EBITDA can provide a useful benchmark for more mature fintech businesses with established profitability. It helps assess value relative to operating earnings, although differences in capital intensity, accounting practices, and financial structure still require careful interpretation.
For certain lending businesses, banks, and other balance-sheet financial institutions, equity-based measures such as Price/Book Value or Price/Earnings may be more relevant than enterprise-value multiples. These businesses require additional consideration of credit exposure, regulatory capital, and funding structure.
No single multiple is appropriate for every fintech company. Selecting the correct benchmark is part of the valuation analysis itself.
Two fintech companies generating similar revenue can trade at substantially different multiples.
A fintech infrastructure provider with recurring revenue, high gross margins, and strong customer retention may command a different valuation than a transaction-based payments company with lower margins and greater exposure to processing costs.
Similarly, lending platforms may face credit losses, funding constraints, and regulatory capital requirements that make direct comparisons with asset-light fintech businesses inappropriate.
Growth rates, profitability, revenue predictability, customer concentration, and market conditions also influence valuation multiples. These factors help explain why broad fintech industry averages often provide an incomplete picture of a company’s value.
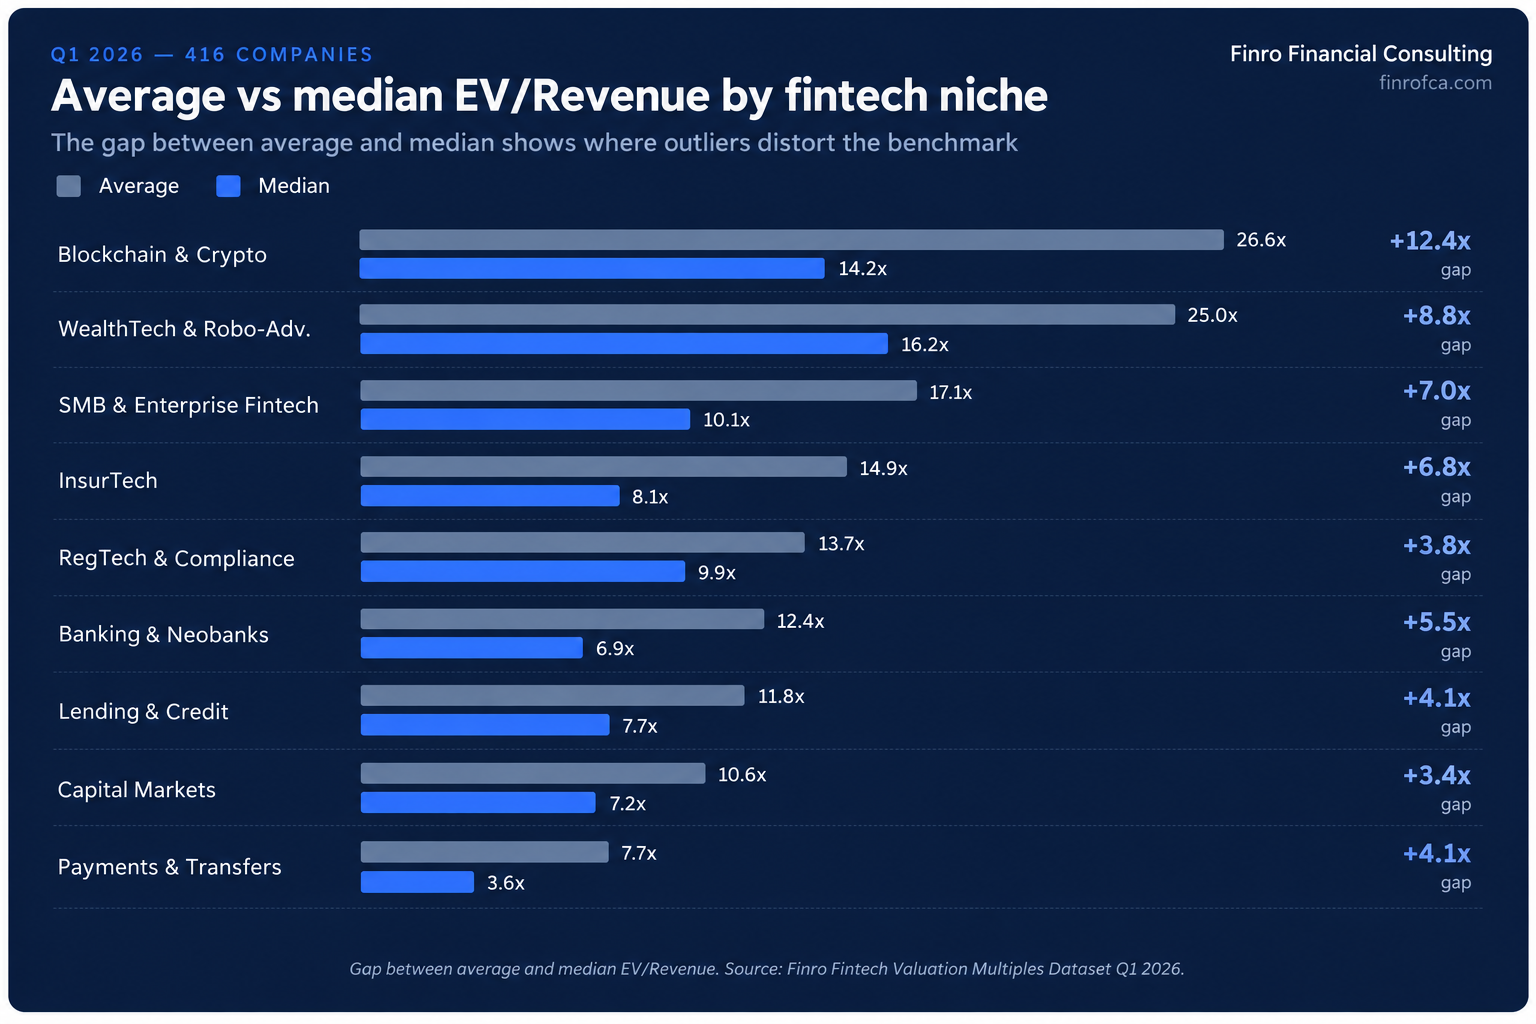
Finro’s Q1 2026 research, covering 416 fintech companies across nine niches, illustrates how significantly valuation multiples differ between business models. The gap between average and median multiples also highlights the risk of relying on broad industry benchmarks without examining the underlying companies.
We use market multiples to establish a valuation range rather than selecting a single industry average.
Our analysis considers relevant public-company trading multiples, private funding valuations, and M&A transaction multiples. We assess each dataset separately, accounting for differences in business models, financial performance, valuation dates, and transaction structures.
We also examine the distribution of observed multiples, including median values, valuation ranges, and potential outliers. Where appropriate, we adjust our interpretation of the benchmarks to reflect differences between the subject company and its comparable universe.
The resulting market-based valuation is then evaluated alongside the company’s financial projections, risk profile, and other valuation methodologies.
This approach helps establish a valuation that reflects both current market evidence and the specific economics of the fintech business being analyzed.
Finro evaluates public-market trading multiples, private funding valuations, and M&A transactions as distinct sources of market evidence.
Reflect current public-market pricing, liquidity, and investor expectations for comparable listed fintech businesses.
Reflect negotiated investment valuations, growth expectations, financing conditions, and security-specific investment terms.
Reflect negotiated acquisition pricing, transaction structure, strategic considerations, and potential control premiums.
These benchmarks are not interchangeable. Finro evaluates differences in transaction structure, valuation date, financial performance, and comparability before using them to establish a market-based valuation range.
Every fintech valuation engagement begins with understanding the company’s business model, financial position, and the purpose of the valuation. Whether the objective is fundraising, an acquisition, or a shareholder transaction, we structure the analysis around the decisions the valuation needs to support.
Our process typically involves four stages, from the initial assessment through the delivery and discussion of the valuation findings.
We begin with a discussion of the company’s activities, development stage, financial position, and valuation objectives.
This helps us identify the appropriate valuation methodologies, the financial information required, and any company-specific considerations, such as regulatory exposure, lending activities, or complex revenue arrangements.
Following this assessment, we define the scope of work, deliverables, and expected timeline.
We review the company’s historical financial performance, existing financial model, and supporting business information.
Depending on the business model, this may include analyzing transaction volumes, recurring revenue, customer economics, credit exposure, operating expenses, and funding requirements.
We also assess the assumptions underlying the financial projections and identify areas requiring clarification, validation, or further analysis.
We perform the selected valuation analyses, which may include discounted cash flow modeling, comparable-company analysis, and relevant M&A transaction benchmarking.
Our market research focuses on companies and transactions with similar financial characteristics, while our financial analysis evaluates the sensitivity of the valuation to key operating assumptions.
We then reconcile the findings to establish a supportable valuation range.
We consolidate the analysis into a valuation report or presentation covering the methodologies, financial assumptions, market benchmarks, and valuation conclusions.
We also walk through the findings with the client, explain the factors influencing the valuation, and address questions about the assumptions and results.
The objective is to provide a valuation that founders, investors, and other stakeholders can understand, evaluate, and use in their financial decision-making.
A fintech valuation engagement should provide more than a single company value or a spreadsheet of financial calculations. Founders and investors need to understand how the valuation was developed, which assumptions influence the results, and how the conclusions compare with market evidence.
At Finro, we tailor our deliverables to the company’s development stage, business model, and valuation objectives. Depending on the agreed scope, a fintech valuation engagement typically includes the following components.
We prepare a valuation report or presentation outlining the company’s financial position, the methodologies applied, and the resulting valuation conclusions.
The analysis explains the key assumptions influencing the valuation, the rationale behind the selected methodologies, and the financial considerations that may affect the company’s value.
Where relevant, we present valuation ranges and alternative scenarios rather than relying on a single-point estimate.
Our supporting analysis includes a review of the company’s financial projections, relevant operating metrics, and the assumptions underlying its expected performance.
We also provide comparable-company and transaction analysis using relevant public companies, private funding rounds, and M&A transactions. This includes the selected valuation benchmarks and an explanation of their relevance to the company’s business model.
Depending on the engagement, the supporting materials may include financial model adjustments, sensitivity analysis, and scenario-based valuation calculations.
We walk clients through the valuation findings, explain the main drivers of the results, and discuss how changes in financial assumptions or market conditions could affect the valuation.
For fundraising or M&A engagements, we can structure the presentation around the questions investors, buyers, or other stakeholders are likely to raise.
The objective is to provide a valuation that clients can use to support investment discussions, evaluate transaction terms, and make informed financial decisions.
Our valuation deliverables combine financial analysis, market evidence, and clear conclusions to support investment and transaction decisions.
A structured assessment of the company's value, including selected methodologies, key financial assumptions, valuation ranges, and conclusions.
Supporting financial analysis, relevant company and transaction benchmarks, and an assessment of the assumptions driving the valuation.
A review of the valuation conclusions, key value drivers, and considerations relevant to fundraising, investment, or M&A discussions.
The exact deliverables depend on the agreed scope of work. Financial model adjustments, additional scenarios, or more extensive market research can be incorporated based on the company's valuation objectives.
Fintech valuations require more than financial modeling expertise. They demand an understanding of how different fintech business models generate revenue, manage risk, and attract investment.
At Finro, we combine financial analysis, technology-sector experience, and proprietary market research to develop valuations tailored to the company’s business model and transaction objectives.
Finro specializes in financial consulting for technology startups, from pre-seed through Series B.
We regularly work with companies that have limited operating histories, evolving revenue models, and ambitious growth projections. Our valuation approach accounts for these characteristics rather than applying the assumptions typically used for established businesses.
This experience is particularly relevant for fintech startups, where the relationship between revenue growth, regulatory requirements, capital needs, and profitability can vary significantly across business models.
A valuation is only as reliable as the financial assumptions and market benchmarks supporting it.
Finro maintains proprietary valuation research covering fintech companies across multiple niches, including publicly traded companies, private startups, and M&A transactions.
We use this research to identify relevant comparable companies, examine valuation multiples, and assess how market pricing differs across fintech business models.
Rather than relying on broad fintech industry averages, we select benchmarks based on the company’s specific revenue characteristics, financial performance, and risk profile.
Our role is to develop a valuation supported by financial evidence, not simply validate a founder’s target valuation.
We challenge financial assumptions, evaluate alternative scenarios, and examine whether the resulting valuation is consistent with relevant market benchmarks.
For fundraising and M&A engagements, we also consider how investors and potential acquirers are likely to evaluate the business.
The result is an independent valuation designed to support informed negotiations and financial decisions, with a clear explanation of the factors driving the company’s value.
Two fintech startups generating the same revenue can have substantially different valuations. A payments platform, digital lender, neobank, and fintech infrastructure provider may operate under different revenue models, regulatory requirements, capital structures, and risk profiles. These differences influence profitability, cash flow, and the valuation benchmarks investors consider relevant.
At Finro, we combine fintech-specific financial analysis, relevant comparable companies and transactions, and company-specific risk assessments to develop independent valuations. Our objective is to provide founders, investors, and boards with a valuation supported by transparent assumptions, market evidence, and a clear explanation of the factors influencing company value.
Independent fintech startup valuation services for fundraising, M&A, and investment decisions. Explore Finro’s specialized approach to fintech valuations.
Independent valuation services for AI startups preparing for fundraising, M&A, or investor negotiations. Expert analysis, financial modeling, and market comparables.
Learn how to accurately value a SaaS business with tailored methods like Revenue Multiple, EBITDA, and DCF. Discover key metrics and why Finro Financial Consulting is the ideal partner for early-stage startups.
How should founders evaluate a startup acquisition offer? Compare the offer with standalone value, future upside, dilution, financing needs, and execution risk.
Explore Q3 2026 EdTech valuation multiples across 296 public and private companies and M&A deals, with benchmarks by niche and funding stage.
Explore 2026 SAFE valuation cap benchmarks and dilution data, and learn how founders can test whether their financial plan supports the next-round valuation.
Explore Q2 2026 Defense Tech startup valuation benchmarks by funding stage, with EV/Revenue multiples, percentile ranges, and analysis from Seed through Late Stage.
Explore Defense Tech valuation multiples across 317 public and private companies and M&A deals, with analysis by niche and funding stage.
Explore the startup funding journey, from initial pre-seed rounds to the strategic exit stage, and learn how each phase supports growth and success.
Learn how to build a startup financial model, forecast revenue, project cash flow, analyze financial statements, and create investor-ready financial projections.
Financial modeling services for startups: learn what an investor-ready model should include, how Finro builds driver-based forecasts, and how to choose the right financial modeling partner.
When do startups need a valuation? Six common triggers explained: fundraising, SAFE conversion, secondaries, M&A, strategic investment, and shareholder disputes.
Why is AI infrastructure investment rising so quickly? We compare AI with 3G, 4G and 5G and explore the theory of investment compression.
Financial due diligence for startups explained: what it includes, common red flags, required documents, timelines, outputs, and when an external review is worth using.
Proptech valuation multiples Q2 2026: EV/Revenue, EV/Funding, funding-stage, and M&A benchmarks across 230 companies and deals in 9 Proptech niches.
Explore the essentials of an Information Memorandum (IM), from crafting compelling executive summaries to detailing financial insights, management teams, and strategic plans for investors.
Analyze the top 10 AI M&A deals by EV/Revenue multiple and learn why buyers pay premium revenue multiples for technical assets, data, workflows, and strategic AI positioning.
No direct comparables? Here is how Finro built a defensible valuation range for a cross-category AI platform using niche decomposition.
OpenAI’s reported financials show why AI revenue multiples can be misleading. Learn why AI valuation depends on cost structure, margins, compute costs, and operating leverage.
Finro analyzes AI M&A revenue multiples by funding stage in Q2 2026, showing why Series A-C targets often command stronger multiples than mature AI acquisition targets.
A practical guide to pre-revenue startup valuation, covering forecasts, market opportunity, valuation methods, execution risk, investor logic, and defensible valuation ranges.
A practical startup financial model readiness guide covering revenue logic, hiring, costs, runway, funding needs, investor questions, and model maturity.
Review your startup financial model before fundraising. Learn what investors look for, common model red flags, and when founders should pressure-test assumptions.
Analyze AI M&A multiples by funding stage using 156 acquisitions. See where AI companies get acquired, where EV/Revenue peaks, and why averages mislead.