Startup Valuation

Startup valuation services built for fundraising, M&A, and investor scrutiny

Finro provides startup valuation services for tech companies preparing for fundraising, M&A, secondary transactions, and investor discussions. We combine relevant market comps with company-specific financial analysis to build a valuation that can stand up to scrutiny.

Typical use cases: priced funding rounds, M&A discussions, secondary transactions, board valuation, and investor-facing valuation support.

Relevant peer set Comparable companies selected by niche, stage, business model, traction, and transaction context.
Defensible valuation logic Revenue, margins, retention, CAC, scenarios, and risk assumptions tied to how the business operates.
Investor-ready deliverable A clear valuation output, supporting analysis, and rationale for fundraising, M&A, board, or investor conversations.

Common valuation situations

When valuation becomes a real decision

Founders, CFOs, investors, and buyers usually come to Finro when valuation is no longer a theoretical exercise. They need to support a funding discussion, evaluate an M&A opportunity, align internally, or explain the valuation logic to someone who will challenge it.

Fundraising

Funding round pricing

Valuation support for priced rounds, SAFE cap discussions, investor negotiations, and fundraising preparation.

M&A

Strategic or exit discussions

Valuation analysis for acquisition interest, sale preparation, strategic alternatives, or buyer conversations.

Internal alignment

Board and shareholder context

Independent valuation work to support internal planning, expectation-setting, and shareholder discussions.

Investor review

Buyer or investor assessment

External analysis for investors, buyers, or finance teams assessing whether a valuation makes sense.

Not sure your situation requires a valuation?

Assess whether valuation is the right next step.

Answer 14 questions about your company, funding history, and upcoming decisions to get an instant valuation assessment.

14 questions Instant assessment No financial data required
Start the assessment

From benchmark to valuation

Startup valuation requires more than market benchmarks. It still needs judgment.

Revenue multiples, funding benchmarks, and M&A datapoints are only the starting point. A defensible startup valuation also depends on stage, business model, growth quality, margins, retention, capital needs, and transaction context.

01

Peer selection changes the answer

A broad sector average can mislead if the company’s niche, stage, business model, revenue maturity, or buyer universe is different.

02

Company quality changes the multiple

Two companies with similar revenue can be valued differently when growth, retention, margins, capital efficiency, or risk profile differ.

03

Context changes the discussion

A valuation for a seed round, secondary sale, M&A process, board discussion, or investor review may require different logic and supporting materials.

Valuation fundamentals

What is startup valuation?

Startup valuation is the process of estimating what a private company is worth based on its stage, business model, traction, financial performance and assumptions, relevant market benchmarks, and transaction context. For fundraising or M&A, a useful valuation should explain why the company is worth what it is, not simply produce a number.

The method depends on the decision.

A fundraising valuation, M&A assessment, secondary transaction, and investor review do not necessarily require the same approach or supporting analysis.

Discuss your valuation

Who Finro supports

Different valuation users, one standard of analysis

Since 2014, Finro has provided startup valuation services to 200+ tech companies and investors across the US, UK, Europe, and other global markets. The work usually sits at the point where valuation needs to be explained to investors, buyers, boards, shareholders, or internal decision-makers.

Founder-led startups

Preparing for a first serious valuation discussion

Startups preparing for a first institutional round, exploring acquisition interest, or trying to understand how investors and buyers may evaluate the business.

Finro helps with: valuation logic, benchmark selection, investor-facing assumptions, and a clear explanation of what supports the valuation.
Pre-seed Seed First fundraise Exit planning
VC-backed startups

Supporting a round, secondary, or board discussion

Companies preparing for fundraising, aligning internally on valuation, reviewing investor feedback, or positioning for a secondary or strategic transaction.

Finro helps with: company-specific valuation analysis, financial model logic, comparable market data, and materials that can withstand investor review.
Series A / B Secondary Board alignment Investor review
Investors and buyers

Testing whether a valuation actually makes sense

VCs, family offices, PE groups, and strategic buyers evaluating investment opportunities, portfolio companies, acquisition targets, or transaction assumptions.

Finro helps with: independent valuation review, comps analysis, assumption testing, due diligence support, and transaction-oriented valuation judgment.
VC / PE Family office Due diligence M&A review

Client proof

Startup valuation used in real fundraising, investment, and transaction decisions

Founders and investors bring Finro in when a startup valuation needs to be supported by independent analysis, defensible assumptions, and financial logic they can explain under scrutiny.

How the engagement works

How our startup valuation process works. Built around the decision you need to support.

Each startup valuation engagement is structured around the decision it needs to support. We align on the valuation context, review the available data, select the appropriate methodology, build the analysis, and deliver an output you can use with investors, buyers, boards, or internal stakeholders.

01

Valuation context and objective

We clarify the purpose of the work, the audience, the decision being supported, and the level of detail required. A fundraising discussion, M&A process, board review, and investor diligence case do not need the same structure.

Output: agreed scope, timeline, and required input list
02

Data review and assumption logic

We review the company’s financials, KPIs, cap table, forecast, business model, and available operating data. The goal is to separate what is supported by evidence from what needs to be framed as an assumption.

Output: data review, assumption map, and key valuation drivers
03

Market benchmarks and method selection

We select relevant public, private, and M&A benchmarks based on niche, stage, business model, revenue maturity, and valuation context. The methodology is chosen around the company and the use case, not forced into a template.

Output: peer set, benchmark analysis, and methodology rationale
04

Valuation output and handoff

Depending on the engagement, the final deliverable may include a valuation memo, presentation, financial model, comps analysis, or supporting valuation materials. The final handoff explains the logic, assumptions, and questions likely to come up.

Output: valuation deliverable and handoff call

Common questions

Startup valuation services FAQ

Practical questions founders, CFOs, investors, and buyers ask before engaging Finro for startup valuation services.

Most valuation projects take 3 to 5 weeks, depending on the company’s stage, data readiness, complexity, and intended use. A focused pre-revenue or early-stage valuation may move faster. A more detailed M&A, investor review, or transaction support engagement may require more work around market data, assumptions, and supporting materials.

Usually we ask for your investor deck, historical financials if available, current forecast or budget, key KPIs, pricing structure, cap table, customer or pipeline data, and any existing valuation assumptions. After the first call, we send a structured input list so the process stays focused.

Yes. Early-stage and pre-revenue valuations rely more heavily on market benchmarks, business model logic, traction signals, team and product maturity, commercial assumptions, and scenario thinking. The key is not pretending there is more data than exists. The key is making the assumptions clear and supportable.

It depends on the engagement. Some clients need a valuation memo or presentation only. Others need a supporting financial model, scenario analysis, comps file, or assumptions review. We define the deliverable upfront based on the decision you need to support and the materials you already have.

Yes, if that is the purpose of the engagement. We can structure the deliverable as an internal decision document, investor-facing valuation summary, board-level analysis, M&A support memo, or supporting material for a transaction discussion. The format should match the audience.

We match on niche, stage, business model, revenue maturity, growth profile, margin structure, and valuation context. Same sector is not enough. A seed-stage fintech application, a growth-stage payments infrastructure company, and a listed fintech platform may all sit inside fintech, but they should not be valued with the same peer logic.

The methodology depends on the company’s stage, available financial data, business model, and purpose of the valuation. Depending on the engagement, we may use comparable company analysis, relevant M&A transaction benchmarks, revenue or EBITDA multiples, DCF where the forecast is sufficiently developed, and other approaches that fit the company’s maturity and valuation context.

Next step

Need a startup valuation you can explain when it is challenged?

Share your stage, business model, and valuation context. We’ll help determine the right approach, required data, and scope before the engagement starts.

Relevant market benchmarks selected for your niche, stage, and valuation context
Company-specific assumptions tied to the business model and available operating data
Clear valuation output for fundraising, M&A, board, investor, or internal discussions
Every engagement led personally by Lior from the first call to the final handoff

Typical first step: a 15 to 20 minute discussion. No obligation.

What to expect

First step 15 to 20 min call
Typical timeline 3 to 5 weeks
Deliverable Defined by use case
Common outputs Memo, model, comps
Obligation None
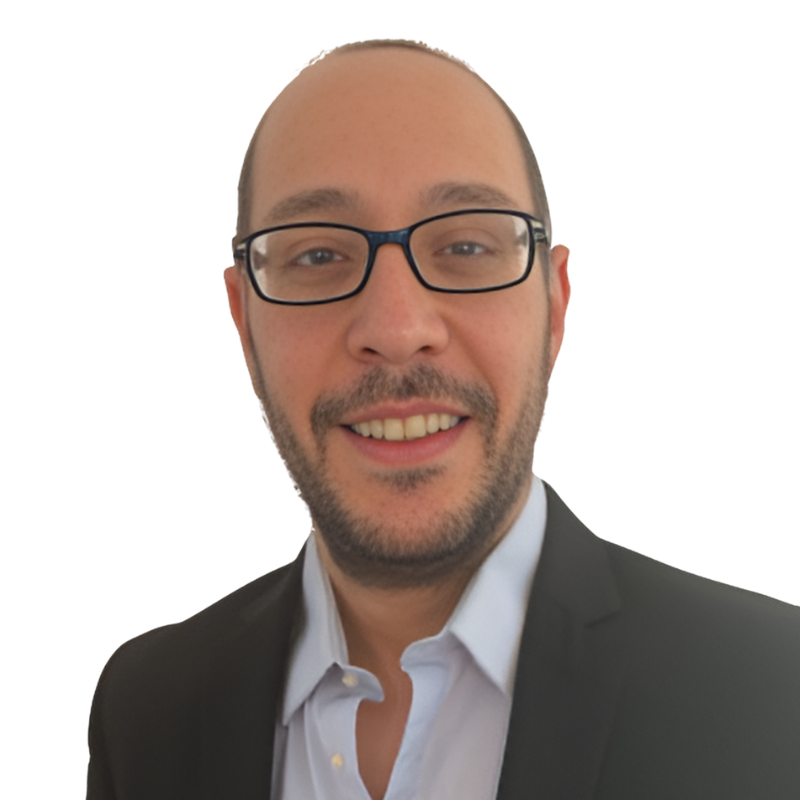
Lior Ronen

Lior Ronen Valuation engagements are led directly by Lior, with no junior analyst handoff.